The challenge is that answering four simple questions can require information from many places. And the stakes are high. Transaction banking is a major revenue engine – McKinsey estimates that it generates almost $1.3 trillion in annual revenue, representing roughly 47% of wholesale banking revenues
1.
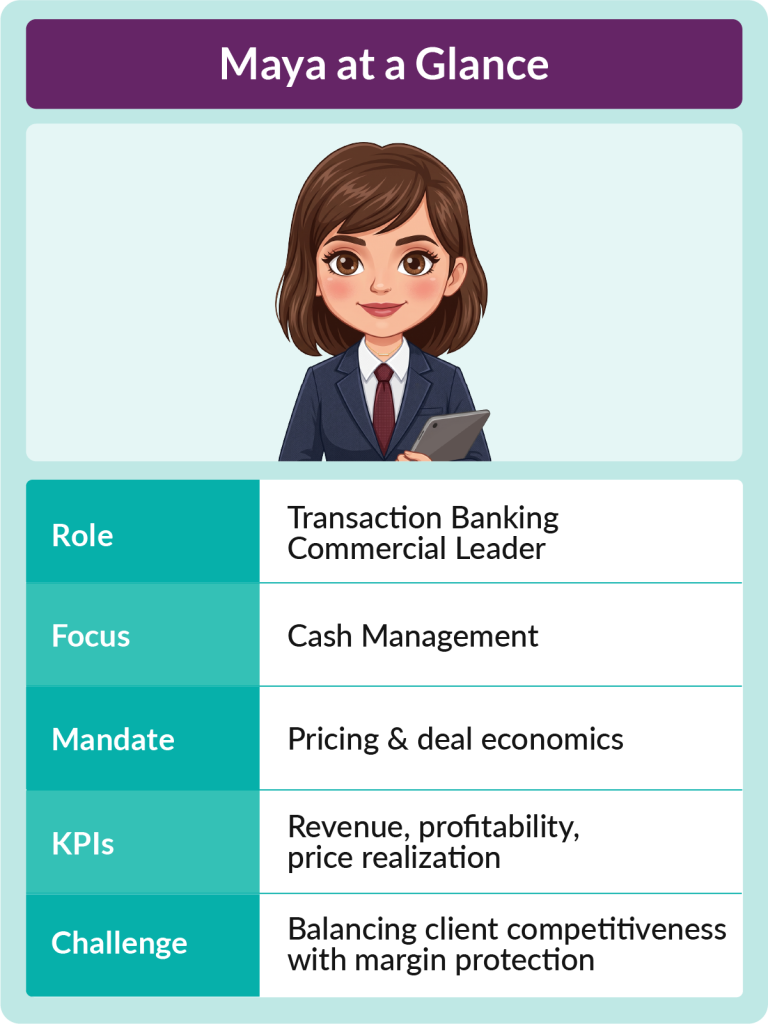
For Maya, even small pricing decisions can have a meaningful impact on the economics of a large and strategically important business.
The Price is Never Just a Price
For a straightforward product, pricing may seem simple. But corporate cash management rarely stays simple for long.
A large client may use multiple services across markets, with different transaction volumes, currencies, account and liquidity structures, and charging models. The relationship may come with negotiated rates, volume-based discounts, waivers, or other commercial terms. An RM may also want to offer concessions based on the broader relationship with the client.
Maya needs to understand all of this before recommending a price.
The information exists. The problem is getting it together quickly enough to make a commercially sound decision.
In many banks, pricing teams still spend significant time pulling information from different systems, spreadsheets, and teams before they can even begin modelling the proposal. And by the time the analysis is complete, the customer may already be waiting for an answer.
For Maya, speed matters. But speed without commercial intelligence can be expensive.
From Pricing Faster to Pricing Smarter
This is where the role of pricing is changing. Maya doesn’t simply need a system that calculates a rate. She needs an intelligent commercial layer that helps her understand what price makes sense for this particular relationship.
Imagine opening the pricing request and immediately seeing the relevant customer economics, historical pricing, comparable deals, and potential profitability of different scenarios.
An AI-assisted recommendation could highlight how similar customers have been priced, identify relevant price benchmarks, and suggest pricing options based on the available data.
Instead of spending days building and comparing scenarios, Maya can get to a commercially informed proposal in hours.
Technology does not make the decision for her.
It gives her better intelligence to make it. That is the difference between automated pricing and intelligent pricing.
The stakes are significant. McKinsey estimates that pricing excellence can improve transaction banking operating profit by 5–10%
2, with structured pricing programs helping banks use better data, customer insights, and pricing guidance to improve commercial decisions.
The Negotiation Doesn’t End When the Price is Agreed
Maya shares her pricing recommendation with the RM. Before it reaches the client, the deal may need to clear several internal checkpoints, including approvals from relevant product teams such as FX, as well as pricing and commercial approvers. Once internally approved, the RM takes the proposal to the client. After several rounds of negotiation, the client accepts. The price is agreed. The deal is won.
But for Maya, two questions matter: Will the bank deliver what it promised? And will the client deliver on its commitments?
The agreement may include preferential rates, volume thresholds, waivers, effective dates, and specific service conditions.
If those commitments sit separately from the pricing decision, they must be translated manually into downstream processes. That is where commercial intent can start getting lost.
A discount agreed during negotiation may not be reflected correctly in billing. A volume-based condition may not be tracked. A new service added to the relationship may not be incorporated into the commercial arrangement. The customer sees one deal. The bank may see several disconnected processes.
The Revenue Journey Doesn’t Stop at Pricing
For Maya, this is why pricing cannot be viewed in isolation.
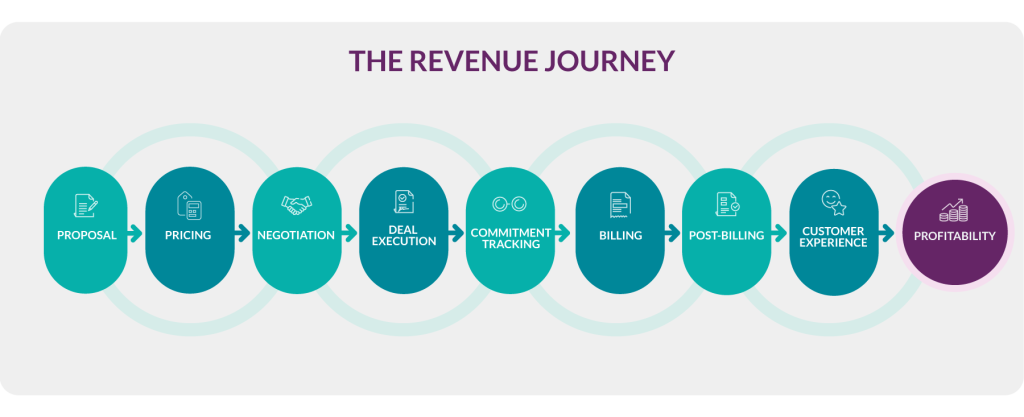
The commercial journey extends from:
Every stage affects the value ultimately realized from the relationship.
If pricing is intelligent but billing cannot interpret the agreed terms, the bank may fail to capture the value it negotiated.
If billing is accurate but the customer cannot understand the charges, the RM inherits the problem.
If a customer disputes an invoice because a negotiated condition was missed, the pricing team may once again have to revisit the original agreement.
The price may have been right. The revenue journey wasn’t.
This is Where the Intelligent Revenue Layer Matters
Maya’s challenge isn’t unique to cash management. The same commercial complexity exists across corporate banking businesses. What changes is the product being sold. The underlying revenue questions remain remarkably similar:
An Intelligent Revenue Layer connects these moments.
For Maya, that means being able to move from customer and market intelligence to pricing scenarios, from negotiated terms to execution, and from execution to accurate billing and profitability. It creates continuity across the commercial lifecycle rather than treating pricing, deal management, and billing as separate activities.
What Changes for Maya?
Six months later, Maya faces another complex pricing request. The complexity has not changed. The bank’s ability to master it has. Customer and market intelligence is available when she needs it. Pricing scenarios can be simulated quickly. Recommendations help her identify commercially viable options. Negotiated terms are connected to the deal. The team has access to the right context and insights, flattening the learning curve for team members. Downstream teams have greater visibility into what was promised. Billing can apply complex commercial arrangements more consistently.
And when the customer asks, “Why was I charged this?”, the bank has a clear answer.
Maya still makes the decisions. She simply spends less time finding, reconciling, and reconstructing information, and more time applying her commercial judgment.
One Deal. One Commercial Story.
Back to Maya’s Monday morning request. The multinational client wasn’t simply asking for a price. It was asking the bank to design a commercial proposition that reflected its needs, the value of the relationship, and the bank’s own economics.
That requires more than a pricing engine. It requires the bank to connect the decisions made before the deal with what happens after it.
For Maya, the goal isn’t simply to price services better. It is to ensure that every commercial decision—from proposal and negotiation to execution, billing, and post-billing is connected to the value the bank intends to create and capture. That is the promise of an Intelligent Revenue Layer.
Because in corporate banking, winning the deal is only one part of the equation. The real advantage comes from knowing what to offer, pricing it intelligently, delivering what was promised, and realizing its full value.